Gross rent and net rental income
Gross rent is the amount received before expenses. A net-income calculation deducts relevant costs under the applicable method. CMHC's framework provides different approaches for specified situations, including whether you live in the property and whether that property is being financed.
A method used for the purchase property should not be assumed to apply to another rental you already own.
A 50% rent example does not calculate your borrowing limit
For a non-owner-occupied two-to-four-unit property being financed, CMHC describes using up to 50% of gross rental income or a net-income approach. If the applicable assessment uses 50% of a $2,000 monthly rent, the assumed income contribution is $1,000 a month, or $12,000 a year.
That example only calculates the rent contribution under the stated assumption. The property's mortgage obligations and the rest of the application still need assessment. It does not establish that every lender uses 50% or tell you how much you could borrow.
Rental cash flow and mortgage qualification are different
Cash flow measures the money a property receives and pays out. Mortgage qualification assesses whether the borrowing meets the relevant lending requirements, using the applicable income treatment and debts. The same rental can therefore affect your cash flow and a lender's assessment differently.
For a portfolio, adding together rent received is not enough. The application needs to show how each property and its mortgage will be assessed alongside the proposed purchase.
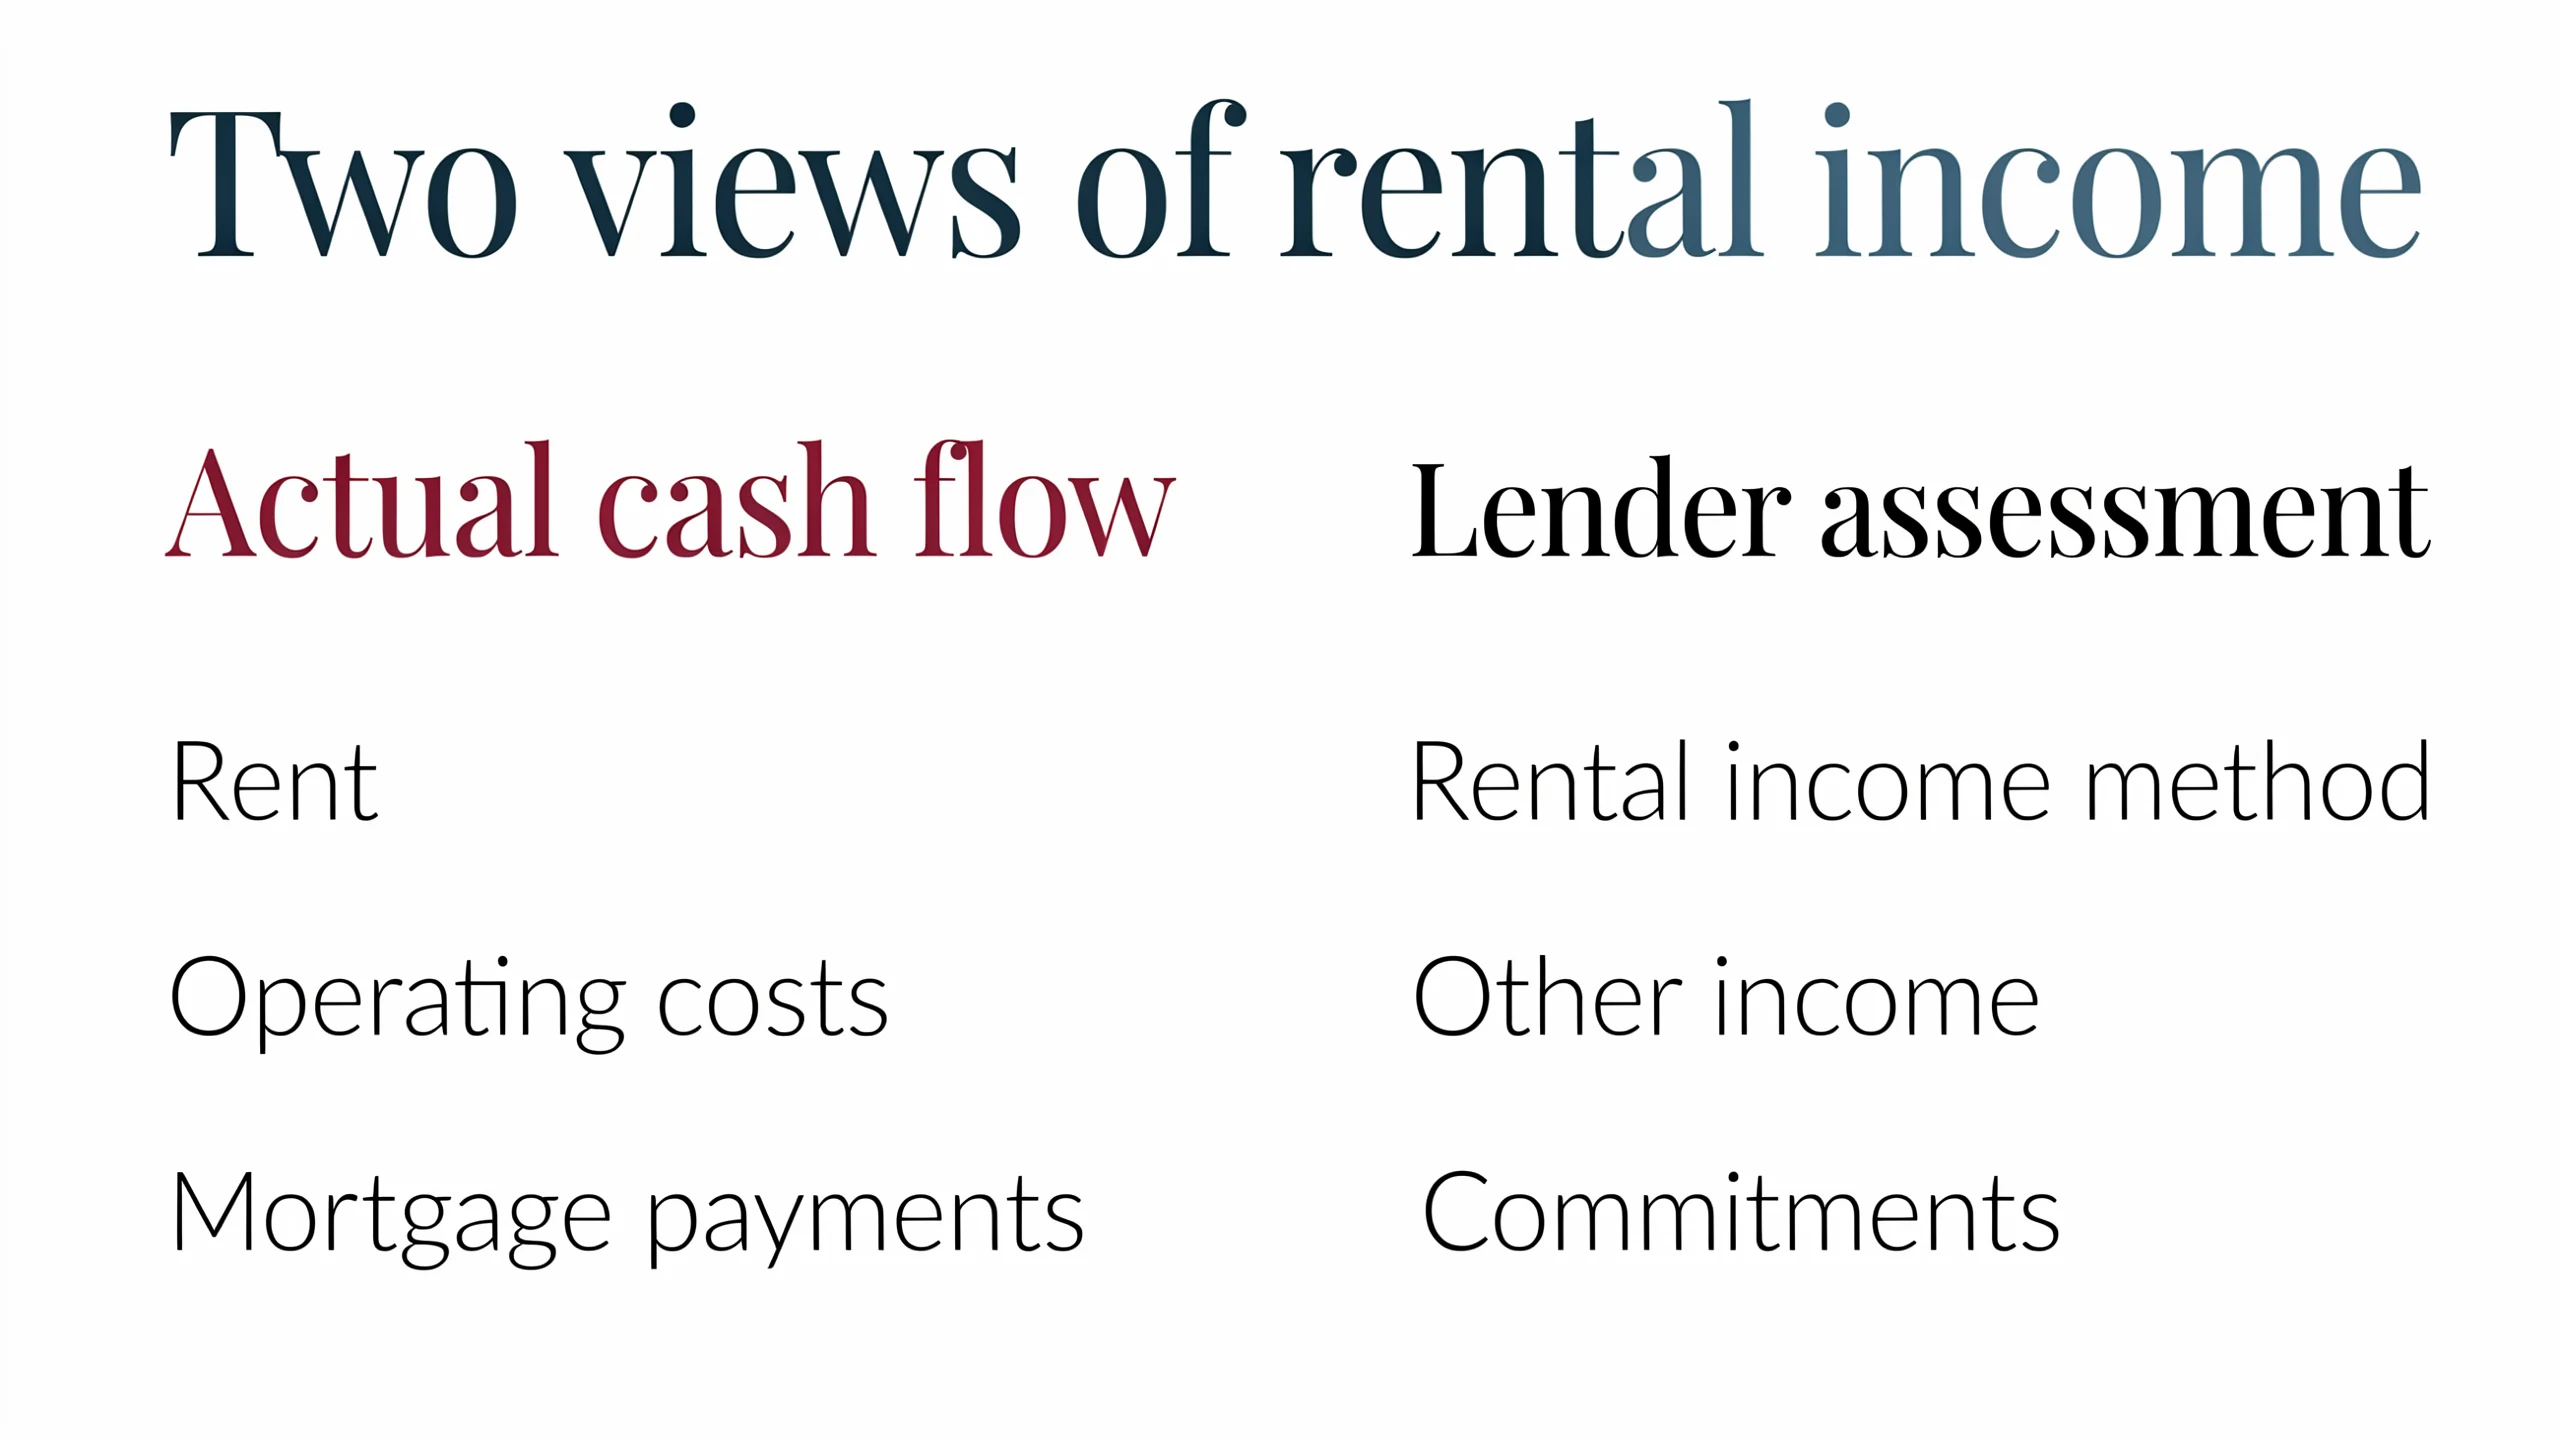
A lender’s treatment of rental income is not a universal percentage or an estimate of borrowing capacity.
Read the graphic description
A cash-flow review considers rent, operating costs and payments. A lender assessment considers its rental-income method, other income, mortgages and debts. A cash-flow result is not a mortgage approval.
Prepare the rental information for your next purchase
Establish which rental-income method applies, what records support the rent and how existing mortgages enter the assessment. If the down payment relies on borrowing against another property, that source of funds needs assessment too. Our equity and refinancing guide explains why equity is not the same as available cash.
Streetwise reviews the proposed purchase alongside your existing rentals, income and mortgages. Read about rental-property financing or contact Streetwise about your application.